Advance tax means paying income tax in instalments during the financial year, instead of in one lump sum at the end. It is often called pay as you earn tax. Here is who must pay it and when.
Who must pay advance tax
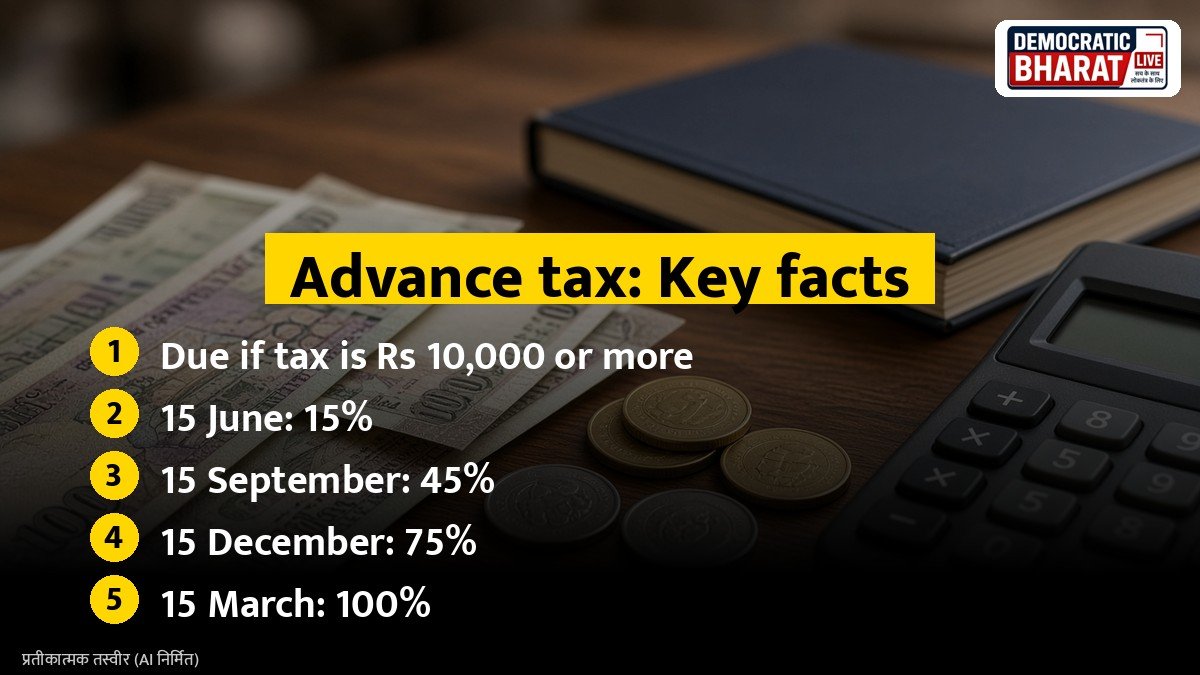
Under the Income Tax Act, you must pay advance tax if your estimated tax liability for the year, after reducing TDS and TCS, is Rs 10,000 or more. This often applies to:
- Freelancers, professionals and business owners
- Salaried people with large income from interest, rent or capital gains
- Investors who earn big gains from shares or property
Who is exempt
A resident senior citizen, aged 60 or above, who does not have income from business or profession does not need to pay advance tax.
Due dates and instalments
For most taxpayers, advance tax must be paid by:
- **15 June:** at least 15 percent of the total tax
- **15 September:** at least 45 percent
- **15 December:** at least 75 percent
- **15 March:** 100 percent
Taxpayers under the presumptive scheme of sections 44AD or 44ADA can pay the entire advance tax in one instalment by 15 March.
Also Read: PPF Account Rules: Deposit Limit, 15 Year Lock In, Loan, Partial Withdrawal and Extension Explained | Senior Citizens Savings Scheme: Rs 30 Lakh Limit, Quarterly Interest, Tax Rules and How to Open
How to calculate
- Estimate your total income for the year from all sources.
- Calculate tax under the regime you plan to choose, old or new.
- Subtract TDS already deducted or expected.
- If the balance is Rs 10,000 or more, pay advance tax in instalments.
Recalculate before each due date, because income such as capital gains can change during the year.
How to pay
Pay online through the e-Pay Tax service on the income tax e-filing portal using challan ITNS 280, selecting Advance Tax (100) as the type of payment. You can pay by net banking, debit card, UPI or other listed modes. Save the challan receipt for your return.
Interest for late or short payment
- **Section 234C:** interest at 1 percent per month for delay or shortfall in each instalment
- **Section 234B:** interest at 1 percent per month if advance tax paid is less than 90 percent of the assessed tax
Interest is calculated on the unpaid amount for the period of delay.
Capital gains in the middle of the year
If you earn capital gains or other unexpected income after a due date, you can include the tax in the remaining instalments. Interest under 234C does not apply for the earlier instalments on such income in many cases.
Bottom line
If your tax after TDS is Rs 10,000 or more, pay advance tax by 15 June, 15 September, 15 December and 15 March to avoid interest.
Source / स्रोत: Income Tax Department, Income Tax e-filing portal