Kisan Vikas Patra (KVP) is a small savings scheme backed by the Government of India. It is simple: your money doubles over a fixed period. Despite its name, anyone eligible can invest, not just farmers. Here is a guide.
Interest rate and doubling period
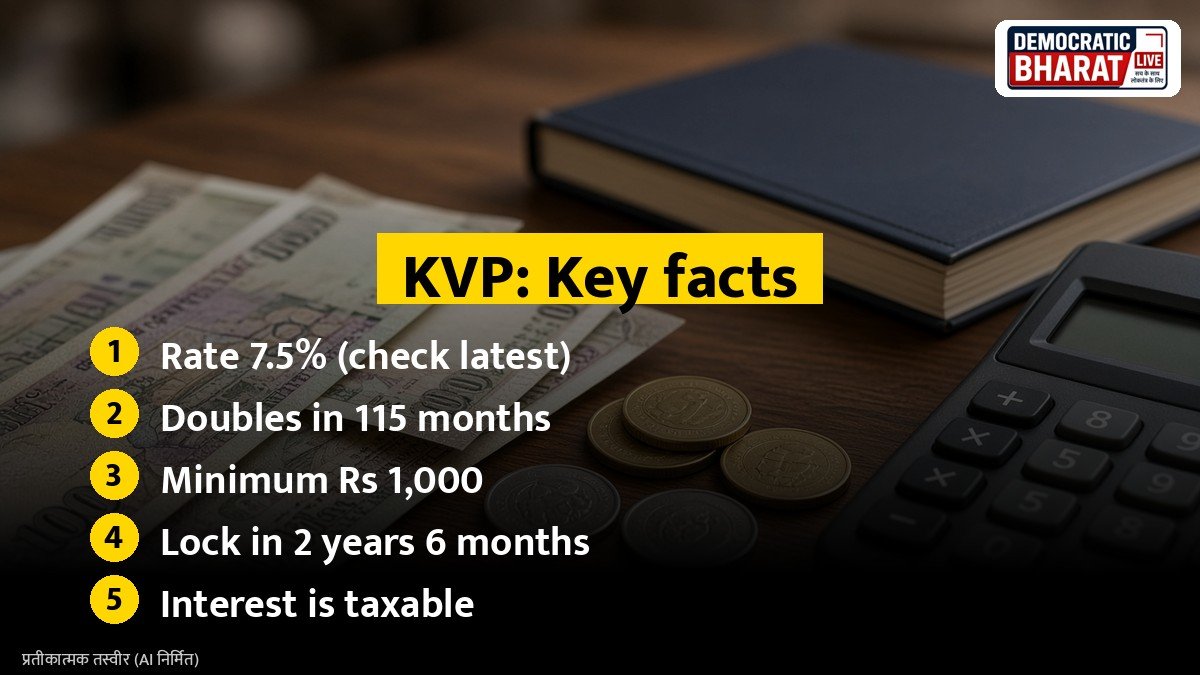
The government reviews small savings rates every quarter. KVP has offered 7.5 percent a year, compounded annually, in recent quarters, which doubles the investment in 115 months, or 9 years and 7 months. Always check the latest rate on the India Post or National Savings Institute website before investing, since the rate applicable on the date of purchase stays fixed for that certificate.
Who can invest
- Any adult resident Indian, singly or jointly with up to three adults.
- A guardian on behalf of a minor or a person of unsound mind.
- A minor aged 10 years or more in his or her own name.
- NRIs cannot open new KVPs.
How much
- Minimum investment: Rs 1,000.
- Further investment in multiples of Rs 100.
- There is no maximum limit.
Also Read: Sukanya Samriddhi Account: Rules, Deposit Limits, Tax Benefits and When the Money Can Be Withdrawn | PPF Account Rules: Deposit Limit, 15 Year Lock In, Loan, Partial Withdrawal and Extension Explained
Lock in and premature closure
- KVP can be encashed after 2 years and 6 months.
- Earlier closure is allowed only in special cases, such as death of the holder or on a court order.
Tax rules
- KVP does not give a deduction under Section 80C.
- Interest is taxable. It can be shown every year on an accrual basis or at maturity.
- There is no TDS on KVP.
KYC rules
- PAN is required for investments above Rs 50,000.
- Proof of income source is required for investments above Rs 10 lakh, as part of anti money laundering rules.
How to buy
- Visit any post office or authorised bank branch.
- Fill the application form.
- Submit KYC documents such as Aadhaar and PAN.
- Pay by cash, cheque or other accepted modes.
- Collect the certificate or passbook.
KVP can be transferred from one person to another in some cases and from one post office to another. It can also be pledged as security for a loan.
Is KVP right for you
KVP suits people who want a guaranteed, sovereign backed return and do not need the money for about ten years. Those wanting tax saving may consider PPF or NSC instead.
Bottom line
Kisan Vikas Patra is a safe, simple way to double money. Check the current rate and remember that interest is taxable.
Source / स्रोत: India Post, Savings Schemes, National Savings Institute, Ministry of Finance, Department of Economic Affairs