

The Atal Pension Yojana (APY) was launched in May 2015 by the Government of India. It is administered by the Pension Fund Regulatory and Development Authority (PFRDA). APY aims to give workers in the unorganised sector a guaranteed pension in old age.
Pension amount
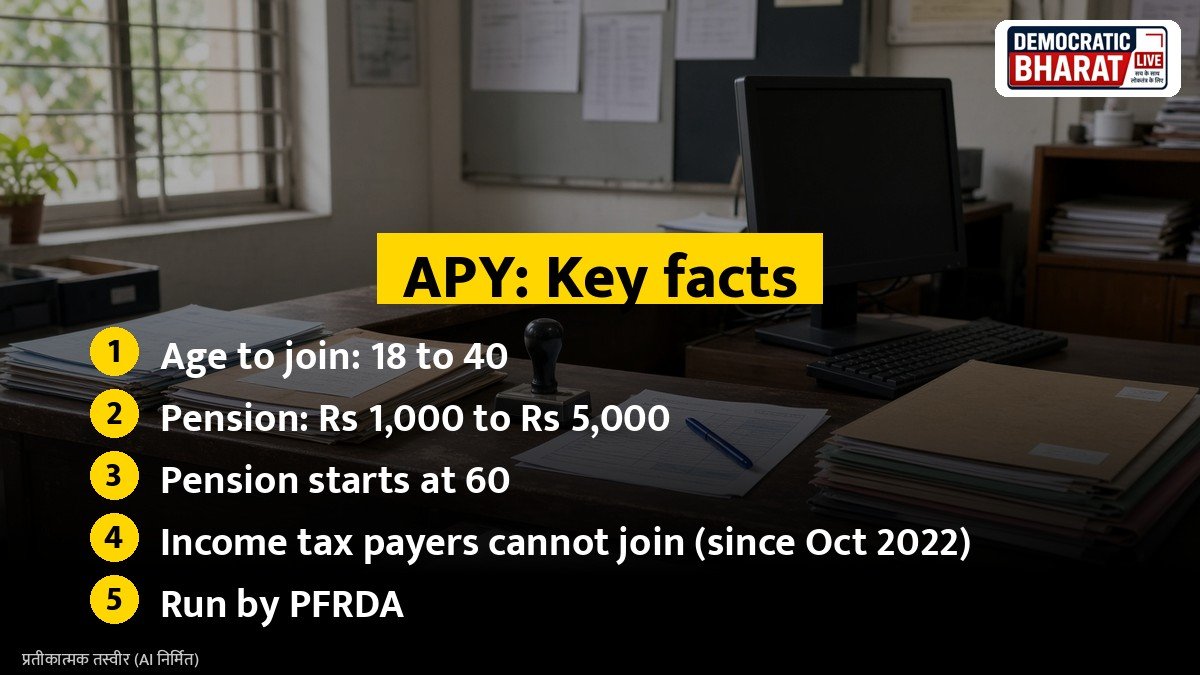
Subscribers can choose a guaranteed monthly pension of Rs 1,000, Rs 2,000, Rs 3,000, Rs 4,000 or Rs 5,000. The pension starts at age 60.
After the death of the subscriber, the same pension is paid to the spouse. After the death of both, the accumulated pension wealth is returned to the nominee.
Who can join
- Any Indian citizen aged 18 to 40 years.
- Must have a savings account in a bank or post office.
- From October 1, 2022, people who are or have been income tax payers are not eligible to join APY, as per a government notification.
How much you pay
The monthly contribution depends on your age at joining and the pension you choose. The younger you join, the lower the contribution. For example, as per the official contribution chart, a person joining at 18 for a Rs 1,000 monthly pension pays a small amount each month, while someone joining at 40 for Rs 5,000 pays much more. Check the full chart on the PFRDA or NPS Trust website before choosing.
Contributions are auto debited from your bank account monthly, quarterly or half yearly, as you choose.
Also Read: PM Ujjwala Yojana: Who Gets a Free LPG Connection, How to Apply and Documents Needed | PM Kisan Status Check: How to See Your Installment, Complete eKYC and Fix Common Problems
How to join
- Visit the bank or post office where you have a savings account, or use the bank’s internet banking or app if it offers APY.
- Fill in the APY registration form with Aadhaar and mobile number.
- Choose the pension amount and contribution frequency.
- Keep enough balance for the auto debit.
Missed payments
If contributions are not paid on time, the bank charges a small penalty as per the rules. Long default can lead to the account being frozen and then closed.
Exit rules
- At 60: the pension starts.
- Before 60: voluntary exit is allowed, but you get back only your contributions and the net actual income earned, not the government co contribution if any was given.
- In case of death before 60: the spouse can continue the account or claim the corpus.
Tax benefit
Contributions to APY qualify for deduction under Section 80CCD of the Income Tax Act, within the limits allowed, under the old tax regime.
Bottom line
Atal Pension Yojana is a low cost way to secure a fixed pension after 60. Join early, choose the pension amount carefully and keep your account funded.
Source / स्रोत: PFRDA: Atal Pension Yojana, National Pension System Trust